

The FX market is relative uncorrelated to other markets which makes it interesting for a diversified portfolio. Unlike other markets the foreign exchange market never really sleeps. As trading moves from Asia to Europe and then to the United States, different investors, firms, and financial intermediaries enter and leave the market at different times. Yet much of what we know about currency returns is based on daily data, which effectively compresses this 24h market into a single number.
Jiang’s paper “Currency Returns in Different Time Zones” asks what we can learn by diving deeper by looking at intraday returns. The paper documents a striking pattern: European currencies tend to appreciate against the US dollar during US business hours, but depreciate during European business hours. So the timing of return measurement is key.
You can read the paper here:
Jiang argues that intraday and overnight currency-return patterns are not merely caused by market segmentation or order flow. They reflect compensation for macroeconomic risk, US macroeconomic news arrives primarily during US business hours. This makes U.S. investors more exposed to long-run economic risk during those hours. Investors therefore demand greater compensation for holding currencies that perform poorly when US economic prospects deteriorate. As a result, European currencies tend to appreciate more during US business hours and depreciate, or appreciate less, during foreign business hours. Conversely, currencies the Japanese yen display the opposite pattern.
In the end, being long a foreign currency-USD pair during the US business hours is an intraday risk premia harvesting trade because US investors demand a premium for holding these risky assets during the time of highest economic risk (most news flow and most transaction flow).
Testing the Theory
Jiang defines the trading period from 10 AM to 4 PM New York time. I use 11 AM to 3 PM. The later starting makes the trading window more realistically feasible for my personal circumstances (job). I also move the end of the trading window one hour earlier. My assumption is that execution quality decreases (wider spreads) around the end of the regular market hours. To avoid this I moved the ending time by 1 hour.
The sample period is from 2021 to 2025. It’s a pretty short window but it is enough for this analysis. The goal of this analysis is to confirm if this effect still exists and can be exploited.
I use a set of 17 exchange rates to monitor currency movements against USD. The universe consists of the 9 G10 currencies, complemented by 8 selected non-G10 currencies (CZK, DKK, HUF, ILS, KRW, MXN, PLN, ZAR).
The selection of the non-G10 currencies is primarily driven by my ability to trade them with Okish costs.
Results
Table 1 summarizes the key performance statistics for the G10 currencies.
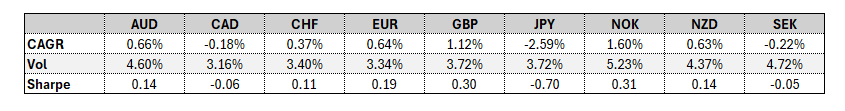
The trading strategy shows mixed results across the 9 G10 currencies. GBP and NOK emerged as the strongest performers. But their Sharpe ratios of around 0.3 are still low. The performance of the other European currencies was indifferent, like the ones of AUD, NZD and CAD. The strong negative performance of JPY confirms the findings of Jiang regarding JPY.
Table 2 summarizes the key performance statistics for the non-G10 currencies.
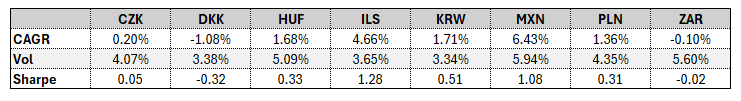
The non-G10 currencies as a group show a materially stronger performance. ILS has the strongest Sharpe: 1.28 by combining good returns with average volatility. MXN has the highest return but also the highest volatility but still manages to get a Sharpe of 1.08. KRW manages to achieve a respectable Sharpe of 0.51. HUF and PLN achieve the same risk-adjusted returns as the top European G10 currencies (GBP and NOK).
My findings suggest that the US business hours risk premium for European currencies isn’t as high as it was when Jiang conducted his analysis. However, I can confirm the negative performance of JPY during US business hours.
In the next step, it’s worth examining the different days of the week and if they have an influence on the results.
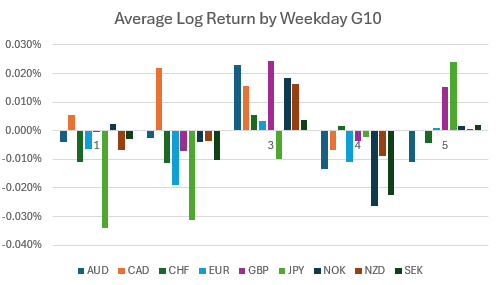
Wednesday is overwhelmingly the strongest day across the G10 currencies. 7 out of 9 currencies generate positive average returns. To the contrary Monday, Tuesday and Thursday look pretty weak. The JPY returns are particularly striking, most of the negative performance is concentrated on Monday and Tuesday.
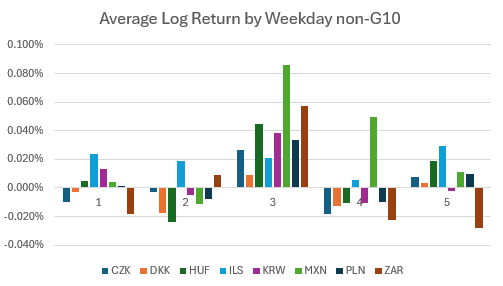
Wednesday returns are even stronger than for the G10 currencies. All non-G10 currencies generate positive average returns. MXN has an exceptional weekday profile. Wednesday and Thursday account for essentially all of the positive contribution. ILS is the most consistent of the group. There is no Wednesday concentration. I think this explains the low to average volatility.
The most obvious conclusion would be that there is a “Wednesday anomaly”, but I don’t buy it yet. It screams data mining. To be sure that this is a real thing there is a bigger analysis (longer timeframe) needed.
Further Work
I also briefly looked at other factors that could potentially enhance the performance of this risk premia harvesting strategy. In particular, I looked at volatility, trend (reversal) and more. So far, none of them had an impact. However this analysis was relatively limited and a more thorough investigating could be worthwhile.
Another important consideration is the set of currencies. So far I only looked at currencies I can trade with reasonable costs. There could be other currencies with even stronger risk premia patterns but you have to able to trade with acceptable trading costs. Therefore, expanding the analysis to a broader set of currencies, while explicitly accounting for realistic transaction costs, could be a useful direction.
Key Takeaways
FX offers diversification benefits
Currency markets are relatively uncorrelated with many other asset classes.
Daily return data can hide important patterns
Jiang’s research identifies a time-zone effect in European currencies. They generally appreciate against the U.S. dollar during U.S. business hours but tend to depreciate during European hours. My research cannot confirm this nor deny it.
Non-G10 currencies performed materially better
The non-G10 currencies outperformed the G10 currencies materially.
The weekday results suggest a possible Wednesday effect
Wednesday produces particularly strong returns across both G10 and non-G10 currencies. However, this may be data mining and requires testing over a longer historical period.
Conclusion
This analysis finds partial evidence that intraday FX returns contain a risk premium during US business hours. While the strong performance of European currencies documented by Jiang is less pronounced in the 2021–2025 sample, except for the effect in the Japanese yen.
The results are more encouraging for selected non-G10 currencies, particularly ILS and MXN, which achieved the strongest risk-adjusted performance.
The concentration of returns on Wednesdays is also noteworthy, but it should be treated cautiously because it may reflect data mining or a sample-specific anomaly. A longer historical sample is necessary to determine whether this pattern is persistent.
Overall, the findings suggest that intraday FX risk premia may exist, but their magnitude and tradability vary considerably across currencies and time periods.
AI Disclosure
Yes, I use AI.
I use it the way some people use a good editor: to trim rambling sentences, fix awkward phrasing, catch typos, tighten structure, and occasionally ask, “Does this argument actually make sense?” Sometimes I’ll even ask it to poke holes in my reasoning or point out weak spots.
I use AI as an editor, not as a thinker.
Every idea, argument, opinion, and conclusion is my own. AI helps me say what I mean more clearly; it doesn’t decide what I mean.
In other words, I outsource the copyediting, not the consciousness.
Disclaimer
The above article constitutes my or the authors’ personal views and is for entertainment purposes only. It is not to be construed as financial advice in any shape or form. Please do your own research and seek your own advice from a qualified financial advisor. I / The authors may from time to time hold positions in the aforementioned securities consistent with the views and opinions expressed in this article. The information provided in this article is not making promises, or guarantees regarding the accuracy of information supplied, nor that you guarantee for the completeness of the information here. The information in this article is opinion-based and that these opinions do not reflect the ideas, ideologies, or points of view of any organization the authors may be potentially affiliated with. The authors reserve the right to change the content of this blog or the above article. The performance represented is historical and that past performance is not a reliable indicator of future results and investors may not recover the full amount invested.
Good article. I'd remove AI disclosure. Who cares? We all use it.